Wiggins Group Real Estate Blog

Stay up to date with new listings, open houses and market news

Check out some of our latest activity and circle back to this page for more real estate updates that impact your buying and selling decisions.

RSS

Buying a Court Ordered Sale in BC: How It Works, and What It Really Costs You

Short answer: A court-ordered sale in BC is a home being sold under the supervision of the BC Supreme Court after a lender forecloses. You buy it as-is with no disclosure statement and no cooling-off period, your offer has to be subject-free before it goes to court, and on the morning of the approval hearing anyone can show up with a sealed envelope and outbid you. The discounts are real but usually modest, because the court's job is specifically to make sure the property doesn't sell for less than it's worth. These work well for buyers with cash, flexibility and renovation capacity. They work badly for anyone on a fixed timeline.

There are more of them on the market right now than at any point in the last twenty years, which is why we're writing this.


How many court-ordered sales are there in BC right now?

More than most people realise, though still a small share of the market.

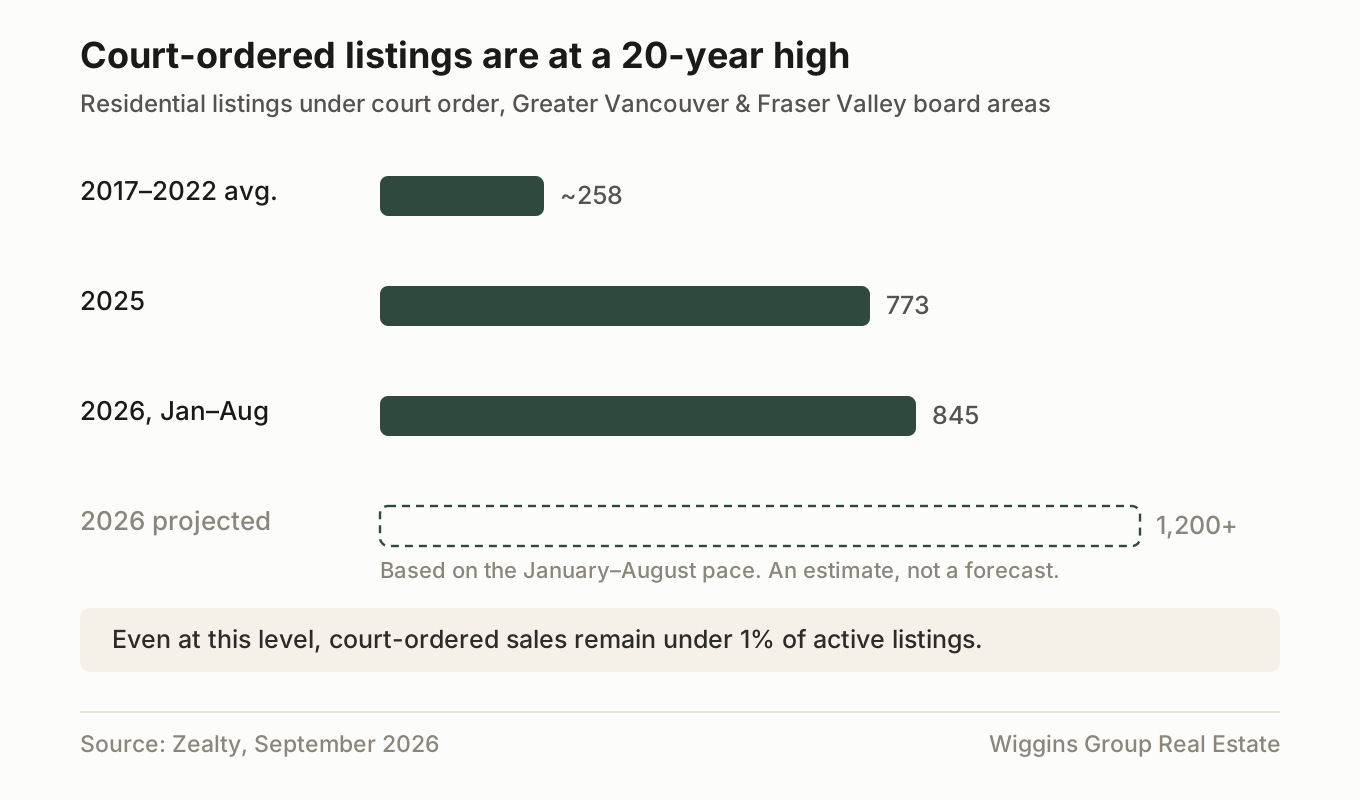
Data from Zealty shows 773 court-ordered listings in 2025 across the areas covered by the Greater Vancouver and Fraser Valley real estate boards — roughly triple the annual average between 2017 and 2022. The first eight months of 2026 alone produced 845, already past the whole of last year. At that pace the year could finish above 1,200 listings, which would be a twenty-year high and would exceed the peak that followed the 2008 financial crisis.

The BC Ministry of the Attorney General has confirmed that the most recent fiscal year hit a ten-year high for foreclosures province-wide.

Two things are worth understanding about this wave. First, it's a lagging indicator — it can take close to a year from a first missed payment to a court-ordered listing, so what you're seeing now reflects financial stress that began well before. Second, it looks different from 2008. Back then court-ordered sales clustered in more affordable areas like the Fraser Valley and the Tri-Cities. This time the activity has shifted up-market, including Vancouver's west side.

Even so, these represent well under one per cent of active listings. This is a real opportunity, not a parallel market.


How the BC foreclosure process actually works

BC does not use power of sale. Everything runs through the Supreme Court of British Columbia, which makes the process slower than in Ontario but considerably more transparent.

1. The lender files a petition

After the borrower defaults, the lender files a petition with the court. The borrower generally has 21 days to file a response.

2. The order nisi

At the first hearing the lender asks for an order nisi — a conditional order of foreclosure. It confirms the default, fixes the exact amount required to redeem the mortgage, sorts out priority among creditors, and sets a redemption period.

Under BC's Law and Equity Act the default redemption period is six months, though a judge can shorten it where there's little equity at stake, or extend it where the circumstances justify more time.

3. The redemption period

This is the borrower's window to fix the situation. They can pay the balance, refinance, or sell the home themselves on the open market. If any of that happens, the foreclosure ends and the property never reaches a court sale.

This matters to you as a buyer. Right up until the court approves a sale, the owner can redeem and the deal evaporates. You can do everything right and still end up with nothing.

4. Conduct of sale

If the redemption period passes without resolution, the lender applies for an order for conduct of sale. This authorises the lender to list and market the property, usually through a realtor, on terms the court sets.

At this point the property appears on MLS like any other listing, typically flagged as a court-ordered sale.

5. Your offer

You write an offer on the standard Contract of Purchase and Sale plus a Schedule A addendum, which is where court-ordered sales diverge sharply from normal transactions. More on that below.

Your offer gets accepted subject to court approval, and all of your own subjects must be removed before the court date. Inspection, financing, title review, strata documents — all done, all at your expense, on a property you do not yet own and may never own.

6. The court approval hearing

This is the part that surprises people.

Your accepted offer is presented to a judge for approval. Under BC Supreme Court Practice Direction PD-66, other buyers may appear at that hearing and submit competing bids in sealed envelopes. They are opened in court that morning.

The judge applies what's often called a providence test — approving the price the court considers fair, and satisfying itself that the sale is provident, meaning it protects the borrower's remaining equity rather than handing a windfall to a bargain hunter.

If a higher bid appears, you can usually improve your offer on the spot. But you're bidding in a room, in real time, against people whose numbers you've just learned.

7. Completion, or an order absolute

Once the court approves, the sale closes much like any other. If no suitable offers come in, the lender can instead seek an order absolute, transferring title to itself.

Typical timeline: roughly three to eight months for the court process, and six to eighteen months from the first default.


What Schedule A actually does to you

This is the single most important document in the transaction, and the one buyers skim.

Sold as-is, where-is. The seller in law is the court, acting through a lender that has never lived in the home and knows nothing about it. There are no representations or warranties about condition, included items, or anything else.

No Property Disclosure Statement. The standard form that tells you about the leaky roof, the buried oil tank or the unpermitted suite simply doesn't exist here.

No Home Buyer Rescission Period. BC's three-business-day cooling-off right does not apply to residential property sold under court order or court supervision. BCFSA confirms this exemption. Once the court approves, you are committed.

Vacant possession is not guaranteed in the way you'd expect. Occupants may still be in the home, and dealing with that can become your problem.

One important limit worth knowing: the as-is clause does not erase a licensee's duty under BC's real estate rules to disclose material latent defects they actually know about. The clause shifts enormous risk to you, but it isn't a licence for anyone to conceal a known serious defect.


The pros

Genuine opportunity in the right circumstances. Properties that need work, unusual properties, or homes with thin buyer pools can trade below what a well-presented equivalent would fetch. The current volume of listings means more of these than there have been in two decades.

Transparency. The process is public and court-supervised. The price has to satisfy a judge. In a normal sale you never learn what the competing offers were.

An unemotional seller. Lenders are not attached to the house and are not negotiating about their children's bedroom. Decisions are commercial.

Less competition from the average buyer. Most buyers won't touch these, which thins the field — though the buyers who remain are usually experienced.

Court oversight cuts both ways. The same process that stops you buying at a steal also means you're unlikely to be caught in a sham transaction.


The cons, including the ones people underestimate

The discount is usually smaller than the folklore suggests. You'll see "10 to 20% below market" quoted widely. Be sceptical. The court's entire function at the approval hearing is to prevent the property selling below fair market value, and competing bidders in the room push the price toward market. Genuine bargains happen where the property is problematic, not simply because it's a foreclosure. Anyone promising you a reliable 20% discount is selling something.

You do the due diligence, then you might lose. This is the real cost. Inspection, appraisal, legal review, strata documents — hundreds or thousands of dollars spent on a property you can lose to a sealed envelope on the courthouse steps. Budget for doing this more than once.

Condition risk is elevated. An owner in financial distress has usually deferred maintenance for a long time. Occasionally a departure isn't gracious. Appliances, fixtures and sometimes worse can be missing. You're buying it anyway.

No disclosure, no recourse, no cooling off. All three protections you'd normally have are gone at once.

The timeline is unpredictable. Redemption can end it at any point. Court dates move. If you need to be in a home by a specific date, this is the wrong path.

Financing can be harder. Lenders are warier of as-is properties, and you need financing firmed up before the court date rather than after. If the home has condition issues, an appraisal may come in short.


Who should actually consider one?

Good fit: buyers with cash or firm financing, flexible timelines, renovation capacity or trades access, and the financial cushion to absorb a surprise after closing. Experienced investors. Buyers who've lost out on a couple and aren't discouraged.

Poor fit: first-time buyers on a tight budget and timeline, anyone who needs to sell an existing home first, anyone without contingency funds, and anyone who'd be emotionally wrecked by losing a home they'd already committed to in their head.

We'd steer most first-time buyers away from these. Not because they can't be done, but because the combination of no disclosure, no rescission period and no margin for a surprise repair is a hard place to learn.


Frequently asked questions

What is a court ordered sale in BC? A property sold under the supervision of the BC Supreme Court after a lender forecloses. Unlike power-of-sale provinces, a judge must approve the sale price.

Are foreclosures cheaper in BC? Sometimes, but less often and by less than people assume. The court's role is to ensure the price is fair to the borrower, and competing bids at the approval hearing push prices toward market value.

Can I put subjects on a court ordered sale? Your subjects must be removed before the court approval hearing. You complete all due diligence at your own expense before you know whether you'll get the property.

Can someone outbid me at the court hearing? Yes. Competing bids may be submitted in sealed envelopes and opened in court on the day. You can generally improve your offer at that point.

Does the cooling-off period apply to a court ordered sale? No. Residential property sold under court order or court supervision is exempt from BC's Home Buyer Rescission Period.

How long does a BC foreclosure take? Commonly three to eight months for the court process, and six to eighteen months from the borrower's first default.

What is an order nisi? The conditional order of foreclosure. It confirms the debt, sets the amount required to redeem, and fixes the redemption period — six months by default under the Law and Equity Act.

Can the owner stop the sale after I make an offer? Yes. Until the court approves, the borrower can redeem by paying what's owed or refinancing, and the sale ends.


If you're facing foreclosure yourself

Some people reading this aren't buyers.

If you've missed payments or received a petition, the most important thing to understand is that the redemption period is genuinely a window, not a formality. Selling on the open market yourself almost always produces a better outcome than a court sale — you keep control of the timing, the price and whatever equity is left.

That gets harder the longer you wait. If you're in that position, talk to a lawyer and get a realistic read on what your home is worth. We're glad to have that conversation with no expectation attached.


Thinking about a court ordered sale?

These transactions reward preparation and punish improvisation. If you want to look at one, we'll walk you through the Schedule A line by line, tell you honestly what we think the property is worth, and give you a realistic view of what it will take to win at the approval hearing — including when we think you should walk away.

We're Denise and Ian Wiggins of Wiggins Group Real Estate at RE/MAX Treeland Realty in Langley, serving Aldergrove, Langley, Surrey, Abbotsford, Mission and the wider Fraser Valley.

604-880-5603 or 604-897-2514 · info@wigginsgroup.ca #101, 6337 – 198 Street, Langley, BC, V2Y 2E3


Foreclosure statistics from Zealty and the BC Ministry of the Attorney General, reported September 2026. This article is general information about the process in British Columbia and is not legal advice. Court procedures and practice directions change — retain a lawyer before making an offer on a court-ordered sale.
Read

Short answer: If you need to move in the next year, list this fall. Sellers have been withdrawing from the Fraser Valley market — new listings in August were down 15% from a year earlier — which means fewer homes competing with yours than in spring, when everyone lists at once. If you genuinely don't need to move and can wait eighteen months or more, waiting is a legitimate choice. What doesn't work is waiting a few months hoping for a better market, because you'd be buying into that same market.

Here's how to figure out which one you are.


What's actually happening with fall listings?

The intuition most sellers have is that spring is when homes sell and fall is when they sit. That's roughly true for buyer traffic. It's not the whole picture.

In August 2026 the Fraser Valley saw 2,373 new listings — down 16% from July and 15% below the same month last year. Sellers are stepping back. Active inventory eased to 9,787, down 3% from July, though still about a third above the ten-year seasonal average.

Meanwhile sales came in at 941, which was 1% above August 2025 — only the second year-over-year gain since the start of 2025.

Put those together: slightly more buying activity than last year, meaningfully fewer new listings. That combination is quietly better for sellers than the headline "buyer's market" suggests.

It is still a buyer's market — the sales-to-active listings ratio was 10%, against 12% to 20% for balanced conditions. But the gap between fall and spring is smaller than most people assume, and the competitive picture may be better.


The spring myth

Spring brings more buyers. It also brings far more sellers.

If you list in April alongside everyone else who spent the winter deciding to move, you're one of a much larger group of similar homes. Buyer traffic goes up, but so does the number of alternatives to your property.

What actually determines whether a home sells is the ratio between demand and competing supply, not the raw number of buyers. A well-priced home in October with fewer comparable listings can outperform the same home in April surrounded by twenty alternatives.

Fall buyers also tend to be more serious. People touring homes in November generally have a reason.


The trap in "waiting for the market to recover"

This is the argument we hear most, and it has a hole in it.

If you're selling and buying — which most sellers are — you don't benefit from a recovery. You sell higher and you buy higher. The two largely cancel out.

In fact, if you're moving up, a soft market works in your favour. A 7% decline on a $750,000 townhouse is about $53,000. An 8% decline on a $1.3 million detached home is about $105,000. The gap you need to bridge has narrowed by roughly $52,000. Wait for a recovery and that advantage disappears.

There's also the rate question. The Bank of Canada has held at 2.25% through six consecutive decisions, and economists surveyed in late August broadly expected no cuts through the rest of 2026, with the next likely move being upward. If you wait a year and prices recover 3% while rates rise, you've gained nothing and possibly lost.


When waiting genuinely makes sense

We'd rather tell you to wait than take a listing that shouldn't exist yet. Wait if:

You don't need to move at all. No job change, no growing family, no financial pressure. A home you're happy in is not an asset you have to optimise.

Your home needs work you haven't done. In a market with this much inventory, a home that shows poorly gets skipped rather than discounted. Six months of targeted work can be worth more than six months of market movement.

You bought recently near the peak and would take a loss you can't absorb. If the numbers don't work, they don't work. Waiting is a real strategy when the alternative is a loss you can't carry.

You're downsizing and can comfortably wait. Downsizers are the one group a falling market genuinely hurts, since your equity drops further in dollar terms than the price of your next home. That deserves its own conversation.


When waiting costs you

You already know you're moving. Every month you delay a decision you've effectively made is a month of carrying costs and uncertainty.

You're moving up. As above — the current spread works for you and will narrow if prices recover.

You're carrying two properties. The math on that rarely improves with time.

It's an estate sale or a separation. Circumstances that need resolution don't get easier by waiting for a season.


What actually determines your result

Not the month. These three:

Price. With inventory this high, an optimistically priced home doesn't just sit — it becomes the comparison that helps a competitor's home sell. Homes priced correctly out of the gate are still moving.

Condition and presentation. Buyers have options. Yours needs to be the one that shows best in its price band, and that's mostly decluttering, minor repairs and good photography rather than renovation.

Realistic expectations about time. Homes are taking longer to sell than they did in 2022. Build that into your plans instead of panicking about it in week four.


Frequently asked questions

Is fall a bad time to sell a house in BC? Not inherently. Fall brings fewer buyers but also fewer competing listings, and fall buyers tend to be more motivated. In the current market, with new listings down 15% year over year, the competitive picture this fall is arguably better than spring's.

Should I wait until spring 2027 to sell my house? Only if you don't need to move, or your home needs preparation work. If you're selling and buying, a market recovery helps you on one side and hurts you on the other.

How long is it taking to sell a home in the Fraser Valley? Longer than in recent years. Check the current FVREB monthly report for average days on market, and plan for a realistic timeline rather than the one you remember from 2021.

Is the Fraser Valley a buyer's or seller's market right now? A buyer's market. The August 2026 sales-to-active listings ratio was 10%; balanced is generally 12% to 20%.

Does listing in December make sense? Rarely. Traffic drops sharply between mid-December and early January. If you're close to that window, either list by late November or plan for a January launch.


Let's look at your specific situation

The right answer here depends on your home, your equity, and where you're going next — not on the calendar.

We're happy to walk through it with you honestly, including telling you if we think you should wait. We'd rather have the right conversation now than the wrong listing in October.

We're Denise and Ian Wiggins of Wiggins Group Real Estate at RE/MAX Treeland Realty in Langley, serving Aldergrove, Langley, Surrey, Abbotsford, Mission and the wider Fraser Valley.

604-880-5603 or 604-897-2514 · info@wigginsgroup.ca #101, 6337 – 198 Street, Langley, BC, V2Y 2E3


Market figures from the Fraser Valley Real Estate Board, August 2026. If you publish after the September report lands in early October, update these. General information only, not financial advice.

Read

Is Now a Good Time to Buy a Home in the Fraser Valley? (August 2026 Update)

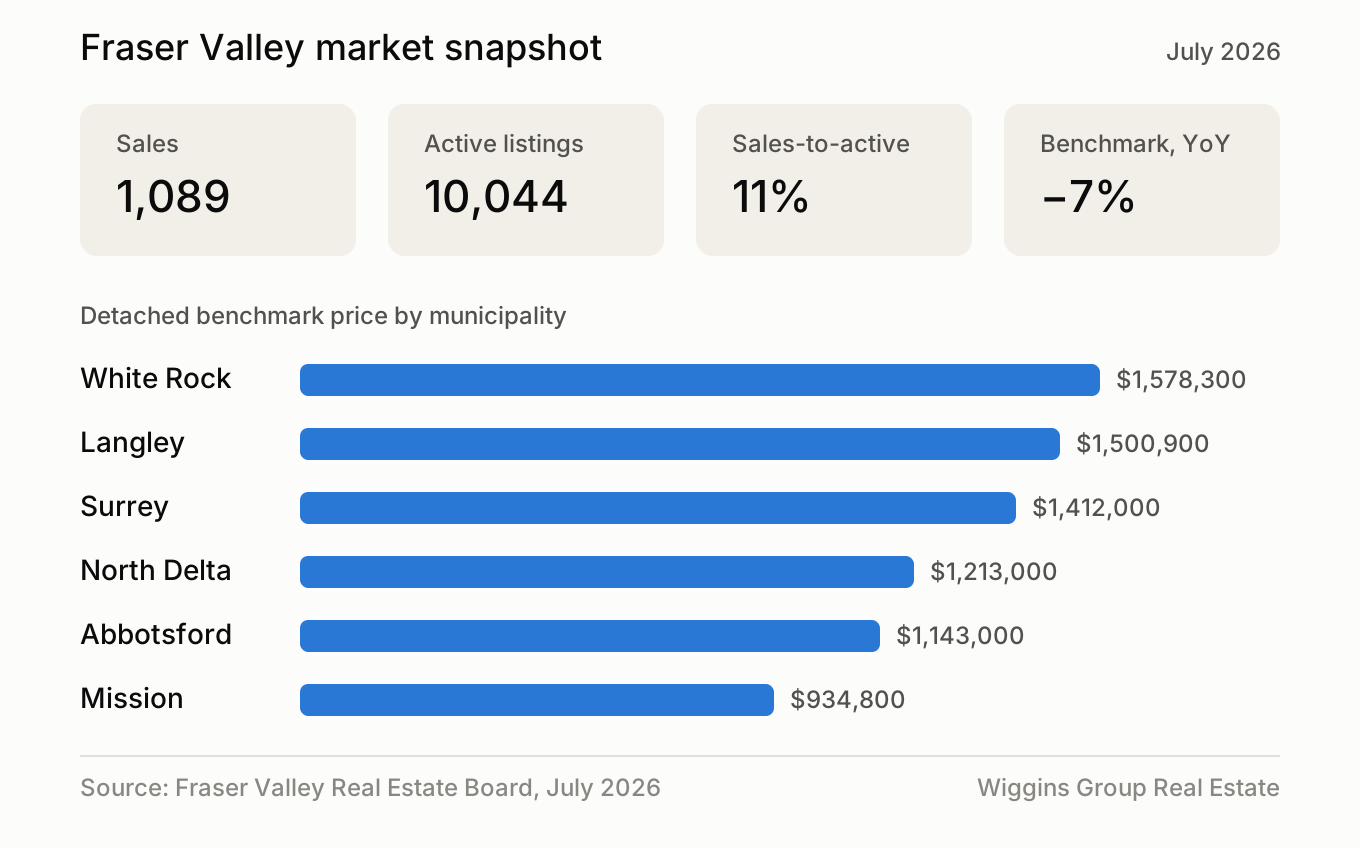
Short answer: For a qualified buyer who plans to stay put for five or more years, yes — this is the strongest negotiating position Fraser Valley buyers have had since 2022. Benchmark prices are down about 7% from a year ago, there were 10,044 active listings on the board in July 2026, and the sales-to-active listings ratio sat at 11%, which is firmly a buyer's market. The trade-off is that mortgage rates are no longer falling, so "waiting for cheaper money" is a weaker strategy than it was two years ago.

Below we break down the current numbers by city, what they mean for buyers and sellers, and the questions we get asked most often at our Langley office.


What is the Fraser Valley housing market doing right now?

The Fraser Valley Real Estate Board's most recent report covers July 2026. Here's where things stand:

Metric (July 2026)NumberChange
Sales1,089Down 5% from June, down 9% from July 2025
New listings2,836Down 14% from June, down 18% from July 2025
Active listings10,044About 32% above the 10-year seasonal average
Sales-to-active listings ratio11%Buyer's market (balanced is 12–20%)
Composite benchmark priceDown 0.8% from June, down 7% year over year

Source: Fraser Valley Real Estate Board, July 2026 Monthly Market Report.

Two things stand out. First, inventory is high but no longer climbing — sellers pulled back in July, with new listings down sharply from both June and last year. Second, buyers are not rushing. Homes are taking roughly 40 days to sell on average, with apartments closer to 46.

That combination is what creates leverage. When a listing sits for six weeks, the conversation changes.


How much have prices dropped in Langley, Surrey, and Abbotsford?

Benchmark prices by municipality, July 2026, with the year-over-year change:

CityDetachedTownhouseApartment
Langley$1,500,900 (−6.2%)$811,400 (−4.8%)$534,200 (−8.9%)
Surrey$1,412,000 (−9.1%)$772,700 (−7.7%)$456,100 (−10.3%)
Abbotsford$1,143,000 (−7.6%)$602,000 (−8.7%)$380,900 (−9.9%)
North Delta$1,213,000 (−9.0%)$848,900 (−8.5%)$496,100 (−10.2%)
White Rock$1,578,300 (−9.5%)$795,900 (−12.6%)$537,700 (−2.7%)
Mission$934,800 (−8.1%)$630,500 (−3.9%)$425,800 (−3.7%)

Source: Fraser Valley Real Estate Board, Municipal Market Report, July 2026. Benchmark price represents a typical home in each category, not an average of sale prices.

For perspective: as of June 2026, Fraser Valley benchmark prices were sitting roughly 26% below their 2022 peak.

A Langley townhouse that would have cost you $852,000 last summer is around $811,000 today. On a 25-year amortization, that difference is real money every month for the next quarter century.


What about mortgage rates? Should I wait for them to come down?

This is the question we get most, and the honest answer is that waiting has gotten riskier.

The Bank of Canada held its policy rate at 2.25% on July 15, 2026 — its sixth consecutive hold. Economists surveyed in late August broadly expect it to stay there through the rest of this year, with the next possible move being a hike rather than a cut. Fixed rates, which follow Government of Canada bond yields rather than the policy rate directly, are currently projected to drift gradually higher rather than lower.

So the strategy of "wait for rates to drop and buy the same house cheaper" no longer has an obvious tailwind behind it. If rates rise while prices flatten out, a buyer who waits could end up paying more per month for the same home.

We're not going to tell you rates will definitely rise — nobody knows. What we will say is that the current window offers something specific and measurable: choice, time, and negotiating room. Those are worth quantifying before you decide to sit it out.


I need to sell before I buy. Am I better off waiting?

Not necessarily, and here's the part sellers often miss.

If you're moving up — say, from a Langley townhouse to a detached home — a falling market usually works in your favour. Yes, you'll likely sell for less than you would have in 2022. But the detached home you're buying has fallen further in dollar terms, because a 6% drop on a $1.5 million house is a much bigger number than a 5% drop on an $811,000 townhouse. The gap you need to bridge has narrowed.

Downsizing runs the opposite way, which is why timing and sequencing matter more for retirees and empty nesters. That's a conversation worth having before you list, not after.

What today's market does demand from sellers is realistic pricing and patience. With inventory 32% above the seasonal norm, an overpriced listing doesn't just sit — it becomes the comparison that helps a competitor's home sell. Homes priced correctly out of the gate are still selling.


Frequently asked questions

Is the Fraser Valley in a buyer's market or a seller's market? A buyer's market. The July 2026 sales-to-active listings ratio was 11%. A balanced market is generally 12–20%, and above 20% favours sellers.

How long does it take to sell a home in the Fraser Valley right now? Roughly 40 days on average for detached homes and townhouses, and about 46 days for apartments, according to the FVREB's July 2026 report.

What is the average price of a house in Langley, BC? The benchmark price for a detached home in Langley was $1,500,900 in July 2026, down 6.2% from July 2025. Townhouses were $811,400 and apartments $534,200.

Are Fraser Valley home prices expected to keep falling? Prices have eased month over month through most of 2026, but the pace has slowed and new listings are declining, which reduces downward pressure. Nobody can forecast this reliably. What's knowable is today's inventory, today's rates, and what a specific home is actually worth.

Which is cheaper, Abbotsford or Langley? Abbotsford, substantially. The July 2026 detached benchmark was $1,143,000 in Abbotsford versus $1,500,900 in Langley — a difference of roughly $358,000 for a comparable typical home.


Talk it through with someone who lives here

We're Denise and Ian Wiggins of Wiggins Group Real Estate at RE/MAX Treeland Realty, a wife-and-husband team based in Langley, BC. We serve Langley, Surrey, North Surrey, Cloverdale, South Surrey/White Rock, North Delta, Abbotsford, Mission, and Chilliwack. Denise was a 2024 FVREB Medallion Club member (top 10% of REALTORS® on the board) and ranked in RE/MAX's top 100 in Western Canada for sales in January 2025.

We're lifelong locals and parents, and our approach is built on clear, honest communication rather than pressure. If you want to know what your specific home is worth in today's market, or what your buying power actually looks like at current rates, we'd be glad to run the numbers with you — no obligation.

Get in touch: 📞 Ian 604-897-2514 Denise 604-880-5603
Email: info@wigginsgroup.ca


Market data in this article comes from the Fraser Valley Real Estate Board's July 2026 Monthly Market Report and Municipal Market Report, and from the Bank of Canada. Chilliwack figures are reported by the Chilliwack and District Real Estate Board and are not included in FVREB statistics. Benchmark prices describe a typical home in each category and are not a substitute for a professional evaluation of your specific property. This article is general information, not financial or legal advice.

Last updated: August 2026.

Read

First-Time Buyer Tax Breaks in BC: New GST Rebate, Property Transfer Tax, and What Langley Buyers Should Know (2026)

Many first-time buyers hear the words rebate, exemption, and tax savings and assume it all means the same thing.

It does not.

If you are buying in Langley or the Fraser Valley, the new federal GST rebate, B.C. property transfer tax, the B.C. first-time home buyers’ program, and the B.C. newly built home exemption are all different. This guide breaks them down in a simpler way so you can understand where the savings may be and where buyers get tripped up.


The quick version

First-time buyers in Langley usually do better when they:

  • separate the federal GST rebate from B.C. property transfer tax

  • understand that resale homes do not qualify for the new GST rebate

  • estimate property transfer tax before they shop

  • check whether they qualify for the B.C. first-time home buyers’ program

  • understand when the B.C. newly built home exemption may apply instead

  • avoid building their budget around best-case assumptions

  • confirm the final numbers with their lawyer, not just online calculators


Step 1: Understand that these are different programs

One of the biggest mistakes buyers make is lumping everything together.

They should not.

Think of it like this:

  • the federal GST rebate is tax relief on qualifying new or substantially renovated homes

  • property transfer tax is a separate B.C. tax paid when title is registered

  • the B.C. first-time home buyers’ program and the B.C. newly built home exemption are separate B.C. programs that may reduce property transfer tax if you qualify

Why this matters

If you mix these together too early, it becomes very easy to misread your true closing costs.


Step 2: Know what the new federal GST rebate actually does

The new federal first-time home buyers’ GST/HST rebate is aimed at qualifying first-time buyers who purchase, build, or substantially renovate a home that will be their primary residence.

For many buyers, the important part is this:

  • qualifying new homes at or below $1 million may qualify for the full rebate

  • the rebate phases down between $1 million and $1.5 million

  • there is no rebate at or above $1.5 million

  • the maximum rebate is up to $50,000

What to remember

This is not a resale-home rebate.

It is aimed at qualifying new or substantially renovated housing.


Step 3: Understand B.C. property transfer tax before you get excited about any rebate

Property transfer tax is separate from GST.

A lot of buyers focus on their down payment and mortgage payment, then forget that property transfer tax may also be due at closing.

That can create a very different cash picture.

Why this matters

Even if you qualify for one rebate or exemption, that does not automatically mean every closing tax disappears.


Step 4: Know what the B.C. first-time home buyers’ program actually saves

This is where buyers often get it wrong.

A lot of people hear the updated threshold numbers and assume that means no property transfer tax all the way up to $835,000.

That is not how it works.

The stronger way to think about it is this:

  • if you qualify and the property is worth $500,000 or less, you may be able to eliminate property transfer tax entirely

  • if the qualifying property is above $500,000 and up to $835,000, you may still get meaningful relief, but you may still owe tax

  • there is then a partial phase-out above $835,000 and under $860,000

Why this matters

This is one of the most misunderstood first-time buyer programs in B.C.

The threshold changed, but that does not mean every qualifying buyer pays zero property transfer tax all the way to $835,000.


Step 5: Know when the B.C. newly built home exemption may apply instead

This program is different again.

The B.C. newly built home exemption is not limited to first-time buyers.

For qualifying buyers, it may reduce or eliminate property transfer tax on a qualifying newly built principal residence.

The broad takeaway is:

  • full relief may be available up to $1.1 million

  • partial relief may apply above $1.1 million and under $1.15 million

  • there are occupancy requirements after closing

What to remember

If you are buying a qualifying new build, this is often the B.C. tax break buyers should understand most clearly.

It is also separate from the federal GST rebate.


Step 6: Do not assume every program stacks the way you hope

Some buyers build their budget around the most optimistic version of every rebate.

That is a mistake.

The better approach is to assume less until the numbers are confirmed.

What to do

  • ask your lawyer or notary to confirm the exact exemption being claimed

  • ask your lender what your real closing cash looks like after taxes and adjustments

  • do not rely on summaries or headlines alone when you are writing offers


Step 7: Use the savings to strengthen your position, not just your budget

If you do qualify for tax savings, the smartest move is usually not stretching farther just because the rebate exists.

A better use of the savings may be to:

  • keep more cash for closing costs

  • build a repair or emergency buffer

  • avoid becoming house poor

  • stay flexible if rates, strata costs, or life changes

Why this matters

A rebate helps most when it makes the purchase safer, not when it pushes you into a weaker position.


Step 8: Build your plan before you shop

Before you start looking at homes, get clear on:

  • whether you are shopping resale or new construction

  • whether you actually meet first-time buyer rules

  • how much property transfer tax you may owe if no exemption applies

  • whether a new build may qualify for the federal GST rebate

  • whether a B.C. property transfer tax exemption may also apply

  • what your real closing cash looks like after all adjustments

That is the difference between shopping with a plan and guessing.


A quick tax break checklist you can screenshot

  • Separate federal GST rebates from B.C. property transfer tax

  • Do not assume resale homes qualify for the new GST rebate

  • Estimate property transfer tax before you start shopping

  • Check whether you actually qualify as a first-time buyer

  • Check whether the B.C. first-time home buyers’ program applies

  • Check whether the B.C. newly built home exemption applies

  • Confirm the final numbers with your lawyer, notary, and lender

  • Build your budget on the conservative version, not the optimistic one


FAQs for first-time buyers in Langley and B.C.

Does the new GST rebate apply to resale homes?

No. It is aimed at qualifying newly built or substantially renovated homes, not regular resale homes.

Is property transfer tax the same thing as GST?

No. They are separate taxes.

Does the B.C. first-time home buyers’ program eliminate property transfer tax up to $835,000?

Not automatically. Buyers can fully eliminate property transfer tax on qualifying homes up to $500,000. Above that, qualifying buyers may still get relief, but they may still owe tax.

Is the B.C. newly built home exemption only for first-time buyers?

No. It is a separate program for qualifying newly built principal residences and is not limited to first-time buyers.


Want help figuring out what actually applies to your situation?

If you are buying your first home in Langley or the Fraser Valley, we are happy to help you sort out the difference between federal rebates, B.C. property transfer tax, and the exemptions buyers often misunderstand.

Wiggins Group Real Estate are local REALTORS® based in Langley, serving the Fraser Valley with a calm, practical approach.

Call or text: Ian 604-897-2514 Denise 604-880-5603
Email: info@wigginsgroup.ca

Read

First-Time Home Buyers in Langley, BC: 8 Things to Do Before You Start Looking (2026)

Buying your first home in Langley can feel like a lot. Between financing, listings, strata documents, and trying not to overpay, it is easy to start looking at homes before you are actually ready.

This guide is written for first-time buyers who want a simple plan before they start booking showings. The goal is not to make the process feel bigger. The goal is to make it clearer.


The quick version

First-time buyers in Langley usually do better when they:

  • get financing sorted before they shop

  • choose property type before neighbourhood

  • understand total monthly cost, not just mortgage payment

  • budget for closing and moving costs

  • take strata documents seriously

  • protect themselves with proper due diligence

  • stay realistic about layout, commute, parking, and resale


Step 1: Know your real monthly comfort zone

A mortgage approval tells you what a lender may allow. It does not automatically tell you what will feel comfortable month to month.

Think about:

  • mortgage payment

  • property taxes

  • utilities

  • home insurance

  • strata fees if applicable

  • internet, parking, and commuting costs

  • basic maintenance and a buffer for surprises

Why this matters

A lot of first-time buyers focus on purchase price and forget how different the monthly cost can feel once everything is added up.


Step 2: Decide what type of home makes sense first

Many first-time buyers in Langley compare condos, townhomes, and older detached homes in the same search.

That usually creates more confusion than clarity.

Ask yourself:

  • Do you want lower maintenance or more space?

  • Is outdoor space important?

  • Do you need two parking spots?

  • Is storage a deal breaker?

  • Are stairs fine or a problem?

  • Are you buying mainly for today, or for the next five years?

Why this matters

Once you know whether you are really looking for a condo, townhome, or detached home, the right neighbourhoods become much easier to compare.


Step 3: Narrow your search area before you fall in love with listings

Langley is not one single market.

Different areas can suit first-time buyers for different reasons depending on budget, commute, and the type of home you want.

First-time buyers often compare areas based on:

  • convenience and walkability

  • access to commuter routes

  • newer construction versus established neighbourhoods

  • condo and townhouse inventory

  • value relative to monthly cost

What to do

  • pick your top two to three areas first

  • compare similar homes in each

  • drive them at different times of day if you can

  • pay attention to parking, traffic, noise, and day-to-day convenience


Step 4: Understand the cash you need upfront

The down payment is not the only number that matters.

First-time buyers should plan for:

  • the deposit once you have an accepted offer

  • closing costs

  • moving costs

  • utility setup and basic home items

  • immediate repairs or purchases after possession

Why this matters

A deal can look workable on paper and still feel tight if you only budget for the down payment.


Step 5: If you are buying a condo or townhome, take strata seriously

This is one of the biggest areas where first-time buyers either protect themselves or create future stress.

Review things like:

  • strata bylaws and rules

  • meeting minutes

  • contingency reserve fund

  • planned repairs or projects

  • restrictions on pets, rentals, parking, and storage

  • monthly fees and what they cover

What to do

  • read the documents early

  • ask questions when something is unclear

  • do not assume a nice complex means a healthy strata

  • understand the rules before you commit, not after


Step 6: Buy based on daily function, not just photos

A beautiful listing can still be the wrong home.

Look past the finishes and ask:

  • Does the layout actually work?

  • Is there enough storage?

  • Does the parking setup make sense?

  • How is the natural light?

  • Where is the unit in the building or complex?

  • What will your commute look like?

  • Will this still fit you in a few years?

Why this matters

First-time buyers often focus on what looks exciting online and miss the details that affect daily life.


Step 7: Protect yourself when you write an offer

Competition can make buyers feel like they need to rush.

That is where expensive mistakes happen.

Depending on the property, common areas of due diligence may include:

  • financing

  • inspection

  • strata document review

  • title and property disclosure review

  • confirming what is included in the sale

What to remember

A fast deal is not automatically a good deal. The goal is not just to win the house. The goal is to buy the right home without creating preventable problems.


Step 8: Know what to walk away from

Sometimes the smartest move for a first-time buyer is not pushing harder. It is stepping back.

Reasons to walk away can include:

  • the monthly cost is tighter than it should be

  • the strata documents raise concerns

  • the layout is wrong for your life

  • the location creates daily friction

  • the property needs more work than you are ready for

  • you feel rushed into accepting risk you do not understand

Why this matters

Your first purchase does not need to be perfect. It just needs to be smart.


A quick first-time buyer checklist you can screenshot

  • Get clear on your comfortable monthly budget

  • Decide what type of home you actually want

  • Narrow your search to two to three realistic Langley areas

  • Budget for more than just the down payment

  • Review strata documents carefully if buying attached property

  • Look at layout, parking, storage, and commute

  • Keep proper due diligence in your offer

  • Be willing to walk away from the wrong fit


FAQs for first-time home buyers in Langley

Is Langley a good place for first-time buyers?

It can be, especially for buyers looking at condos, townhomes, and selected entry-level options depending on budget and location. The key is matching the right area and property type to your actual budget and lifestyle.

Should a first-time buyer start with a condo or a townhouse?

That depends on your priorities. Condos may offer a lower-maintenance starting point, while townhomes may give you more space and flexibility. The better choice is the one that fits your monthly comfort zone and day-to-day needs.

What should first-time buyers watch for in Langley?

Start with total monthly cost, property type, neighbourhood fit, strata health if applicable, and whether the home will actually work for your daily life.


Want a calm plan before you start looking?

If you are buying your first home in Langley or the Fraser Valley, we are happy to help you build a clear plan before you start chasing listings. A good first step is not seeing more homes. It is getting clearer on budget, property type, neighbourhood, and risk.

Wiggins Group Real Estate are local REALTORS® based in Langley, serving the Fraser Valley with a calm, practical approach.

Call or text: Ian 604-897-2514 Denise 604-880-5603
Email: info@wigginsgroup.ca

Read

City of Langley vs Township of Langley: What Home Buyers Need to Know (2026)

Many buyers start by saying they want to live in “Langley,” but there is an important detail that gets missed all the time.

The City of Langley and the Township of Langley are two separate municipalities. If you do not understand that early, it becomes much harder to compare homes, neighbourhoods, commute options, and property types properly.

This guide is written to help buyers understand the difference before they start chasing listings.


Step 1: Understand that “Langley” does not mean one thing

When buyers say they want to move to Langley, they can mean very different things.

Some are picturing a condo close to shops and services. Others want a detached family home with a yard. Others want more privacy, more land, or even an acreage.

Why this matters

The City of Langley and the Township of Langley offer different lifestyles, different housing options, and different search starting points.

If you mix them together too early, you waste time looking at the wrong properties.


Step 2: Know what the City of Langley usually offers

The City of Langley is smaller and more urban in feel.

Buyers often look here for

  • walkability

  • easier access to shops and services

  • condo and townhouse options

  • lower maintenance living

  • a more central and connected feel

Good fit for

  • first time buyers

  • downsizers

  • buyers who want convenience over lot size


Step 3: Know what the Township of Langley usually offers

The Township of Langley is much larger and includes a wider range of neighbourhoods and property types.

Areas in the Township include

  • Walnut Grove

  • Willoughby

  • Murrayville

  • Brookswood

  • Fort Langley

  • Salmon River

  • Campbell Valley

  • Aldergrove

Buyers often look here for

  • detached family homes

  • larger lots

  • suburban neighbourhoods

  • rural or semi-rural living

  • acreage and lifestyle properties


Step 4: Match the area to your lifestyle, not just your budget

A lot of buyers start with price and then try to force the neighbourhood to fit.

That is backwards.

Better questions to ask first

  • Do you want walkability or more space?

  • Do you need quick commuter access?

  • Do you want a newer home or an established neighbourhood?

  • Do you want a yard, shop space, or future flexibility?

  • Are you buying for the next 3 years or the next 10?

Why this matters

The right choice is not about which area is “better.” It is about which area fits your real day to day life.


Step 5: Do not assume pricing works the same everywhere

This is one of the biggest mistakes buyers make.

They assume Langley is one market and expect homes across the City and Township to compare cleanly.

They do not.

Pricing can vary based on

  • municipality

  • neighbourhood

  • property type

  • lot size

  • school catchment

  • age and condition

  • walkability

  • access to amenities and commuting routes

What to do

  • compare similar property types

  • compare within the same neighbourhood where possible

  • avoid using broad averages as your main filter


Step 6: Think about best fit by buyer type

Some areas make more sense depending on what stage of life you are in and what you need from the property.

First time buyers

The City of Langley may offer more practical entry points, especially for condos and townhomes.

Growing families

The Township often gives buyers more detached home options, more yard space, and more family-oriented neighbourhood choices.

Lifestyle and acreage buyers

The Township is where the serious search usually happens if you want land, privacy, outbuildings, or room for hobbies and animals.

Downsizers

The City may appeal if convenience and lower maintenance matter most. Some Township neighbourhoods may also fit if you still want quiet surroundings and more space.


Step 7: Avoid the most common mistake

The biggest mistake is being too vague.

Saying “we want Langley” is not a real filter.

Get clear on

  • the type of home you want

  • how much space you need

  • your commute tolerance

  • whether walkability matters

  • whether you want newer construction, established neighbourhoods, or more land

The clearer you get on that, the easier it becomes to narrow the right part of Langley.


A quick Langley buyer checklist you can screenshot

  • Confirm whether you are searching in the City, Township, or both

  • Decide whether convenience or space matters more

  • Choose your preferred property type first

  • Narrow your search by lifestyle, not just price

  • Compare neighbourhoods separately instead of lumping them together

  • Be realistic about what your budget buys in each area

  • Think about long term fit, not just current emotion


FAQs about buying in the City of Langley vs the Township of Langley

Is the City of Langley the same as the Township of Langley?

No. They are separate municipalities and they offer different housing types, neighbourhoods, and lifestyle options.

Is the Township of Langley better for detached homes and acreages?

In many cases, yes. The Township includes a wider range of detached home neighbourhoods and rural or lifestyle property areas.

Is the City of Langley better for first time buyers?

It can be a strong option for first time buyers, especially those looking for condos, townhomes, and a more connected location. This depends on budget and property type.


Want help figuring out which part of Langley fits you best

If you are deciding between the City of Langley and the Township of Langley, we can help you narrow the search based on your budget, lifestyle, and long term goals before you waste time on the wrong homes.

Wiggins Group Real Estate are local REALTORS® based in Langley, serving the Fraser Valley with a calm, practical approach.

Call or text: Ian 604-897-2514 Denise 604-880-5603
Email: info@wigginsgroup.ca

Read

How to Choose a REALTOR® in Langley, BC: 10 Questions to Ask Before You Hire One (2026)

Choosing the right REALTOR® is one of the biggest decisions you will make in the buying or selling process. In a market like Langley and the Fraser Valley, the difference between a good fit and the wrong fit often shows up in pricing strategy, negotiation, due diligence, and how calm you feel throughout the process.

This guide gives you 10 questions to ask before you commit, plus a few red flags to watch for. It is written for real people who want straight answers and a smooth experience.

If you are new to the area, you might also like our Living in Langley, BC guide and our Acreage Due Diligence Checklist.


The quick version

A great REALTOR® in Langley should be able to:

  • explain the process clearly

  • guide you through due diligence and risk

  • price and market strategically

  • negotiate confidently

  • communicate consistently

  • know the local neighbourhoods and property types


10 questions to ask a REALTOR® in Langley

1) Do you work primarily in Langley and the Fraser Valley?

Langley is not one single market. City of Langley and Township of Langley can feel very different, and neighbourhoods vary a lot.

Listen for:

  • specific local examples

  • familiarity with neighbourhood differences

  • a clear idea of what buyers in Langley care about right now


2) What areas do you know best, and why?

Some agents say they serve everywhere. The best ones can tell you where they are strongest.

Ask:

  • What neighbourhoods do you work in most often

  • Where are buyers moving from

  • What types of homes do you handle most


3) How will you help me avoid overpaying or underselling?

This is the heart of the job.

A strong answer includes:

  • how they evaluate comparable sales

  • how they adjust for condition, lot, layout, and location

  • how they handle multiple offers or soft demand

  • how they talk about risk, not just price


4) What is your process from start to finish?

You want a clear plan, not vague confidence.

Ask them to walk you through:

  • your first call and planning stage

  • showings and shortlisting

  • writing an offer and conditions

  • inspections and document review

  • negotiations

  • completion, possession, and after care


5) How do you handle inspections and due diligence?

If you are buying, this matters more than most people realize. If you are selling, your agent should know how to reduce surprises.

Good signs:

  • they encourage proper due diligence

  • they explain conditions clearly

  • they can recommend specialists when needed

  • they do not push you to waive protections without a clear reason


6) What is your experience with my property type?

In Langley, the strategy changes depending on what you are dealing with.

Ask directly if they have experience with:

  • condos and strata documents

  • townhomes and complex strata rules

  • detached homes and lot value

  • acreages and rural considerations such as zoning, wells, septic, outbuildings

If you are looking at lifestyle property, this is non negotiable.


7) How do you communicate, and how often?

This is where many relationships fall apart.

Ask:

  • will you update me weekly even if nothing is happening

  • do you prefer text, phone, or email

  • what is your typical response time

  • who covers you if you are unavailable

You want clarity, not guessing.


8) How do you market a listing?

If you are selling, your marketing should match buyer behavior.

Ask:

  • how they prepare the home for photos and first impressions

  • what their listing launch plan looks like

  • how they handle showing windows, open houses, and follow up

  • how they measure whether the price is working

A good answer is specific and process based.


9) What is your negotiation style?

Some agents negotiate with pressure. Some negotiate with strategy. The best negotiators protect your goals and keep emotions from taking over.

Ask:

  • how they structure offers and counteroffers

  • how they handle multiple offer situations

  • how they reduce risk while still staying competitive

  • how they advise when a deal is not worth it


10) Can you share a few recent examples or references?

You are not asking for confidential details. You are looking for patterns.

Ask:

  • what types of clients they helped recently

  • what challenges came up

  • how the agent solved them

  • whether they can share a few client reviews or references


Red flags to watch for

These do not always mean someone is a bad agent, but they are worth paying attention to.

  • they cannot clearly explain their process

  • they avoid discussing risk and due diligence

  • they pressure you to move faster than you are comfortable with

  • they talk more than they listen

  • they promise outcomes that no one can guarantee

  • they do not know the neighbourhood details for where you want to buy or sell


What to prepare before you meet a REALTOR®

You will get better advice if you bring:

  • your ideal timeline

  • your must haves and deal breakers

  • your commute or lifestyle priorities

  • your comfort level with renovations

  • your rough budget range

  • the neighbourhoods you like so far

If you are selling, add:

  • your ideal move date

  • any known updates or repairs

  • what you think makes your home different


FAQs about choosing a REALTOR® in Langley and The Fraser Valley

Do I need to sign a contract right away

Not always. It is reasonable to meet, ask questions, and make sure it is a fit before you commit.

What makes Langley different from other areas

Langley includes a wide mix of neighbourhoods and property types, and the City of Langley and Township of Langley are different municipalities. Local experience matters.

Should I work with a REALTOR® who specializes

If you have a specific property type, such as acreages, lifestyle properties, or complex strata, a specialist helps you avoid expensive mistakes.

How do I know if pricing advice is good

A good agent will show you comparable sales, explain adjustments, and discuss risk. They should be able to defend their recommendation with clear reasoning.


Want a calm second opinion before you choose

If you are buying or selling in Langley or the Fraser Valley, we are happy to answer these questions with you and help you build a clear plan.

Wiggins Group Real Estate are local REALTORS® based in Langley, serving the Fraser Valley. We specialize in acreages, lifestyle properties, and family homes, with a practical approach and clear communication.

Call or text: Denise 604-880-5603 Ian 604-897-2514
Email: ian@wigginsgroup.ca

Read

Buying an Acreage in Langley or the Fraser Valley: A Due Diligence Checklist (2026)

Acreages and lifestyle properties can be incredible. More space, more privacy, room for a shop, hobbies, animals, or just breathing room. They also come with a different set of questions than a typical residential home in Langley.

This guide covers the due diligence steps we recommend before you commit to an acreage in Langley or the Fraser Valley. It is written to help you avoid surprises and feel confident in what you are buying.


Step 1: Confirm what you are allowed to do with the property

Before you fall in love with the view or the shop, confirm the basics.

Zoning and permitted uses

Ask what the zoning allows. This affects things like:

  • keeping animals

  • adding outbuildings

  • operating a home based business

  • building a secondary suite or additional dwelling

ALR considerations

Some properties are in the Agricultural Land Reserve. That is not a deal breaker, but it can affect permitted uses and future plans. Make sure the property matches what you want to do long term.


Step 2: Water supply, well systems, and water quality

Water is one of the biggest differences between rural and standard residential homes.

Key questions

  • Is the property on a private well, community system, or municipal water?

  • If it is a well, what is the well depth and age if known?

  • Are there recent water quality tests available?

  • What is the water flow like for household use and irrigation?

What to do

  • Request any records the seller has

  • Consider a water test and well flow test where appropriate


Step 3: Septic system type, age, and condition

Septic is another major acreage factor and it needs to be understood early.

Key questions

  • What type of septic system is it

  • How old is it and when was it last serviced

  • Are there service records or permits available

  • Has there been any past backup or repair work

What to do

  • If possible, arrange a septic inspection or review of available records

  • Confirm the system fits the number of bedrooms and intended use


Step 4: Property lines, access, and easements

A property can look perfect and still have limitations.

Key things to check

  • Confirm boundaries and lot shape

  • Identify easements, right of ways, and statutory rights of way

  • Confirm driveway access and whether any portion is shared

  • Watch for access limitations that affect future outbuildings or fencing


Step 5: Drainage, ditches, and winter performance

Acreages can behave very differently across seasons.

What to look for

  • standing water after rain

  • soggy sections of pasture or yard

  • drainage around outbuildings and foundations

  • culverts and ditch maintenance

What to do

If you can, visit after rainfall and ask how the property handles heavy rain and winter conditions.


Step 6: Outbuildings, shops, barns, and permits

Many buyers are purchasing an acreage for the shop, barn, or extra structures.

Questions to ask

  • Were structures built with permits

  • What electrical service is in the shop

  • Any known issues with roof, drainage, slab cracking, or wiring

  • Are there existing inspections or contractor invoices

Even if permits are not available, you still want to understand condition, safety, and replacement costs.


Step 7: Utilities and service capacity

Lifestyle properties can have a mix of utility setups.

Confirm

  • electrical service size and capacity

  • heating source and age

  • internet options

  • garbage and recycling service

  • propane or oil systems if applicable

If you work from home or plan to run equipment, service capacity matters.


Step 8: Trees, slopes, and environmental considerations

Large properties often come with natural features that need maintenance.

Consider

  • tree risk near the home and driveway

  • steep slopes and soil stability

  • creeks, wetlands, or riparian setbacks

  • fencing needs and ongoing maintenance

These are not meant to scare you. They are meant to help you budget and plan realistically.


Step 9: Your lifestyle plan and ongoing costs

Acreage ownership is a lifestyle choice. It is worth mapping your plan.

Think about

  • time required for maintenance

  • equipment needs such as a mower, tractor, or snow removal

  • fencing and animal care if applicable

  • seasonal work and drainage upkeep

A good acreage purchase feels exciting, and also realistic.


A quick acreage buyer checklist you can screenshot

  • Confirm zoning and permitted uses

  • Confirm ALR status and implications

  • Identify water source and test if needed

  • Inspect septic or review available records

  • Review easements and access

  • Assess drainage and winter performance

  • Evaluate outbuildings and shop condition

  • Confirm utility capacity and internet options

  • Consider tree risk and environmental features

  • Budget for equipment and ongoing upkeep


FAQs about buying acreages in Langley and the Fraser Valley

Is buying an acreage in Langley different from buying a regular house

Yes. Water, septic, zoning, access, and outbuildings often become major factors. Due diligence needs to match the property type.

Are acreages in the Fraser Valley always in the ALR

Not always. Some are, some are not. It is important to confirm early because it can affect permitted uses.

What inspections should I consider for a lifestyle property

A standard home inspection is a good start. Many buyers also consider well and water tests, septic review, and specialist assessments for outbuildings or shops.


Want a second opinion before you write an offer

If you are looking at an acreage in Langley or the Fraser Valley, we are happy to help you think through the due diligence before you commit. A quick conversation can save a lot of stress later.

Wiggins Group Real Estate are local REALTORS® based in Langley, serving the Fraser Valley. We specialize in acreages and lifestyle properties with a calm, practical approach.

Call or text: Ian 604-897-2514 Denise 604-880-5603
Email: info@wigginsgroup.ca

Read

Living in Langley, BC: A Local Guide for Home Buyers, Families and Lifestyle Property Owners (2026)

Thinking about moving to Langley or buying your next home here? Langley is one of those places people choose for more space and then stay for the community. Whether you are a first-time buyer, upsizing for a growing family, or looking for an acreage with room to breathe, this guide will help you understand the area and plan your next steps with confidence.

This is a local, practical guide. No hype, just useful info.


Why people choose Langley

Space and variety

Langley offers a wide range of housing options. You will find newer subdivisions, established neighbourhoods with mature trees, townhomes and condos near amenities, and rural pockets that still feel connected.

Community feel

It is a big reason families land here. Parks, sports, schools, and local events make Langley feel like a place where you can put down roots.

Location without the downtown lifestyle

You are within reach of major routes and employment hubs, but many people move here for a more balanced pace and more breathing room.


City of Langley vs Township of Langley

This clarification saves confusion early.

  • City of Langley is smaller and more concentrated with convenience and walkability in some areas.

  • Township of Langley is much larger and includes a wide range of neighbourhoods plus rural areas.

This can affect services, neighbourhood options, and what “Langley” means in a listing. It is always worth confirming which municipality you are looking in.


Neighbourhood vibes in plain language

Fort Langley

Historic village feel with strong community identity. Great if you love charm, walkability, and a weekend coffee and stroll lifestyle.

Willoughby and Yorkson

A common landing spot for families and move up buyers. Many newer homes and townhomes, schools, and ongoing development.

Walnut Grove

Established, family friendly, and popular for buyers who want a classic suburban feel with good access to amenities.

Murrayville

A mix of established homes and newer options. Often appealing to families who want a quieter vibe and larger lots.

Aldergrove

More small town feel and often better value for space. A good option if you like Langley but do not need to be in the center of everything.

Salmon River and rural pockets

This is where lifestyle property starts to show up. More land, outbuildings, hobby farm potential, and extra due diligence.


Buying in Langley: what surprises people

Competition changes block by block

Two similar homes can sell very differently depending on the street, school catchment, walkability, lot shape, and future development nearby.

Commute reality is personal

Some people accept a longer commute if they get the yard, the shop, or the community. Others need to be closer to their daily route. Map your commute early so you do not fall in love with a home that does not fit your weekdays.

Newer does not always mean less maintenance

New builds can be great, but every home type has its own watch outs. The goal is not new versus old. The goal is right fit plus solid due diligence.


First-time buyers in Langley: a simple checklist

If you are buying your first place here, focus on these:

  • Monthly payment comfort, not maximum approval

  • Strata documents if buying a condo or townhome

  • A clear inspection strategy that matches your risk tolerance

  • Resale reality, even if this is a starter home

A good REALTOR® should be able to explain the process in plain language and help you avoid common first purchase mistakes.


Buying an acreage or lifestyle property

Acreages can be incredible and they require a different kind of due diligence. Here are the big buckets to think about.

Water and septic

  • Is it on a well or city water

  • What type of septic system is it and what is its condition

  • Are records available

Zoning and ALR considerations

Some rural properties come with restrictions or land use rules. That is not bad, it just needs to match what you want to do with the land.

Outbuildings and shops

Shops can be a huge value add. Check permits where possible, plus electrical, drainage, and overall condition.

Drainage, access, and year round usability

A property can look perfect in summer and behave differently in winter. Ask how it handles heavy rain, driveway access, and drainage.


Selling in Langley: what actually moves the needle

A successful sale usually comes down to a few key factors:

  • Pricing strategy that matches buyer psychology

  • Presentation including photos, staging, and the first impression online

  • A clear marketing plan

  • Negotiation that protects your bottom line


Quick FAQs about Langley real estate

Is Langley a good place to buy a home in 2026?
Langley remains popular because it offers a balance of space, community, and access to the broader region. The right time depends on your budget, goals, and timeline.

What are the best areas in Langley for families?
Many families consider Willoughby, Walnut Grove, Murrayville, and parts of Aldergrove depending on schools, commute, and housing type. The best area is the one that fits your day to day life.

What should I watch for when buying an acreage in Langley or the Fraser Valley?
Start with water, septic, zoning, access, drainage, and outbuildings. Lifestyle property can be an amazing fit as long as the due diligence matches the dream.

City of Langley vs Township of Langley, does it matter?
It can. They are separate municipalities and the differences can show up in services, neighbourhood options, and local considerations. It is worth clarifying early when you are searching.


Want a local second opinion on your plan?

If you are thinking about buying or selling in Langley, or looking at an acreage in the Fraser Valley, it helps to talk it through with a local team who can give you clear guidance.

Wiggins Group Real Estate are local REALTORS® based in Langley, serving the Fraser Valley. We specialize in acreages, lifestyle properties, and family homes with a calm, practical approach.

Call/Text Denise - 604-880-5603.   Call/Text Ian - 604-897-2514

Read

Langley Real Estate FAQs: Answers to the Questions We Get Asked Every Week

If you’re thinking about buying or selling a home in Langley, you probably have a lot of questions — and you’re not alone. These are the same questions we get asked every single week by buyers and sellers just like you.

This FAQ-style guide is designed to give you clear, honest, local answers so you can make confident real estate decisions without feeling overwhelmed.


How long do homes typically take to sell in Langley?

The time it takes to sell a home in Langley depends on several key factors:

  • Current market conditions (buyer’s vs. seller’s market)

  • Price compared to similar homes

  • Location and neighbourhood

  • Condition and presentation of the home

In a balanced market, most well-priced homes in Langley sell within 30–60 days. In a buyer’s market, homes may take longer to sell, while homes priced correctly in high-demand areas can sell more quickly.

Overpricing almost always leads to longer days on market and eventual price reductions.


Is it a good time to buy or sell in Langley right now?

This depends largely on your goals.

Buyers may benefit from more choice and negotiating power during slower markets. Sellers tend to benefit most when inventory is low and buyer demand is strong.

What matters most is aligning your timing with your personal situation — not trying to perfectly time the market. A strategy tailored to your goals usually matters more than market headlines.


Do I need a home inspection when buying a house?

In most cases, yes.

A professional home inspection can uncover roof, foundation, or structural concerns, as well as electrical, plumbing, moisture, drainage, or ventilation issues.

While some buyers choose to waive inspections in competitive situations, it’s important to understand the risks before doing so. If you’re early in the process, our Langley Home Buyer Guide walks you through inspections, financing, timelines, and common mistakes to avoid before you write an offer.

You can read the full guide here:
https://wigginsgroup.ca/buying.html


How much do I need for a down payment in BC?

Minimum down payment requirements in Canada (including BC) are:

  • 5% on the first $500,000 of the purchase price

  • 10% on the portion from $500,000 to $999,999

  • 20% on homes priced at $1,000,000 or more

These rules are set federally and apply across the country.

First-time buyers in BC may qualify for programs that can help reduce upfront costs, such as the First-Time Home Buyers’ Program (which may reduce or eliminate Property Transfer Tax on qualifying purchases) and the First Home Savings Account (FHSA), which allows buyers to save for a down payment on a tax-advantaged basis. Eligibility depends on purchase price, property type, and individual circumstances.

In addition to the down payment, buyers should also budget for closing costs such as legal fees, inspections, property transfer tax (if applicable), and moving expenses.


Can I buy a home before selling my current one?

Yes, but it requires careful planning.

Options may include bridge financing, longer completion dates, selling first and negotiating rent-back, or strategically aligning possession dates.

Each option has pros and cons depending on your finances, risk tolerance, and current market conditions. Getting advice early can reduce stress and prevent costly mistakes.


What is my home worth in Langley?

For an accurate price, a custom market evaluation based on recent comparable sales is essential. If you’d like a clearer picture of your home’s value in today’s Langley market, you can request a custom home evaluation here:

https://wigginsgroup.ca/home-evaluation.html

If you’re considering selling, our Langley Home Seller Guide explains pricing strategy, preparation tips, timelines, and what to expect throughout the selling process.

https://wigginsgroup.ca/selling.html


Are basement suites legal in Langley?

Not all basement suites are created equal.

In Langley, legality depends on zoning, ceiling height, fire separation, and parking requirements. Some homes have authorized suites, others are non-conforming, and some are unauthorized.

Knowing the difference matters for financing, insurance, and resale value.


What costs should sellers expect when selling a home?

Common selling costs include real estate fees, legal fees, mortgage discharge penalties (if applicable), and moving costs.

Many sellers also choose to invest in minor repairs, staging, and professional photography to help their home stand out online and attract more buyers.

At Wiggins Group Real Estate, professional photography is included with every listing. We believe high-quality photos are essential to showcasing a home at its maximum potential — especially in today’s market, where most buyers form their first impression online. Professional photography ensures your home is presented accurately, beautifully, and competitively, rather than relying on casual or low-quality images.


Do I need to sell or buy first?

There’s no one-size-fits-all answer.

Selling first reduces financial risk but may require temporary housing. Buying first offers certainty but requires stronger financial planning.

The right approach depends on market conditions and your comfort level with risk.


Ready to Talk About Your Move in Langley?

Whether you’re just starting to think about buying or selling, having clear local information makes the process far less stressful.

If you’re planning to sell, our Langley Home Seller Guide explains pricing, timing, and how to prepare your home for today’s market.
https://wigginsgroup.ca/selling.html

If you’re thinking about buying, our Langley Home Buyer Guide walks you through the process step by step so you know what to expect before you begin touring homes.
https://wigginsgroup.ca/buying.html

If you’d like advice tailored to your situation, we’re always happy to help.

Read

Christmas Events in Aldergrove 2025: Parades, Markets, Tree Lighting & Zoo Lights

Here’s our roundup of Christmas events in Aldergrove and nearby for 2025, including parades, markets, tree lightings, and brand-new Zoo Lights.

November and December are full of community spirit in Aldergrove — a time to reflect, remember, and celebrate together. From the Remembrance Day Parade to school craft markets, the annual Tree Lighting, and December’s Christmas Light Up Parade, there’s plenty happening around town.


Remembrance Day Parade & Ceremony

Date: November 11
Time: Parade 10:45 AM, Service 10:50 AM
Location: Aldergrove Legion – 26607 Fraser Hwy

Each year, our community gathers to honour the courage and sacrifice of those who served. The Aldergrove Legion hosts the parade and ceremony, bringing together veterans, families, and residents in a heartfelt tribute of remembrance.


Holiday Craft Markets

Aldergrove’s schools are hosting their much-loved holiday craft markets throughout November — a perfect way to shop local and support our community:

  • North Otter Elementary – 5155 248 St – November 8 | 10 AM–3 PM

  • Coghlan Fundamental Elementary – 4452 256 St – November 15 | 10 AM–3 PM

  • Parkside Elementary – 3300 270 St – November 21 (4:30–7 PM) & November 22 (10 AM–3 PM)

  • Shortreed Elementary – 27330 28 Ave – November 29 | 10 AM–3 PM


4th Annual Aldergrove Tree Lighting Event

Date: Sunday, November 23 | 4–6 PM
Location: Aldergrove Community Centre Parking Lot (270th St & Fraser Hwy)

The community gathers to officially kick off the holiday season with Aldergrove’s annual Tree Lighting.


Christmas in Aldergrove: Light Up Parade & Community Party

Date: Saturday, December 13, 2025
Location: Downtown Aldergrove (270th St & Fraser Hwy)

Aldergrove’s annual Christmas Light Up Parade runs through downtown on December 13, 2025.
Join the Pre-Parade Community Christmas Party from 4:00–6:00 PM at 270th Street and Fraser Highway for food, hot beverages, and entertainment — and yes, Santa will be there! More details HERE!

Interested in joining the parade? Float and entry applications are open until Monday, December 8, 2025 on the Aldergrove Fair website.


Merry & Bright at Martini Town (Langley)

Date: November 21 – December 31, 2025
Time: Wednesday to Sunday, 3:00 PM – 10:00 PM (closed Mondays & Tuesdays; closed Christmas Day)
Location: Martini Town, 1123 272 Street, Langley

Martini Town turns into a real-life Christmas movie set every winter, and it’s only a few minutes from Aldergrove. Walk through a glowing holiday village, peek into themed storefronts, grab a warm treat, and take all the festive photos you want. Tickets are sold in advance with timed entry, so it’s best to book ahead. More details HERE!


Zoo Lights at the Greater Vancouver Zoo (Aldergrove!)

Date: November 22, 2025 – January 10, 2026 (closed Dec 25)
Time: 4:00 PM – 9:00 PM (last entry 8:00 PM)
Location: Greater Vancouver Zoo, 5048 264 Street, Aldergrove

This is a brand-new holiday event in Aldergrove and we’re so excited to have it right here in our own backyard. The Greater Vancouver Zoo transforms into a sparkling walk-through lantern and light experience with themed displays and cozy winter vibes — a perfect bundle-up evening for families, and a great new tradition to kick off the season locally. Tickets are required, so plan ahead if you’re hoping to go on a weekend. More details HERE!


Santa Paws Photos (Clearview Garden Centre)

Date: Saturday, November 29, 2025
Time: 10:00 AM – 4:00 PM (book a time slot online)
Location: Clearview Garden Centre / Clearview Country Market, 26350 56 Avenue, Langley

If your pets are part of the family (and let’s be honest, they are), this is such a cute holiday outing. The Langley Animal Protection Society has Santa stopping by for festive photos with your furry friends, and humans too. Sessions are $40 and include two digital images, with proceeds supporting local animals through LAPS. Be sure to book your time slot online ahead of time. More details HERE!


Stay Connected

Aldergrove is truly special — a place where community events bring neighbours together all year long.
Follow us for more local updates, real estate insights, and upcoming community highlights:
📱 @wigginsgroup_realestate | @Wiggins Group Real Estate

Read

🏡 5 Essential Things to Know Before Buying or Selling Acreage Properties

🌿 Introduction

Buying or selling an acreage is about more than just land — it’s about understanding the unique systems and responsibilities that come with rural living. From wells and septic systems to zoning rules and access roads, every property tells its own story.

Below is our Fraser Valley acreage buyer and seller checklist to help you avoid surprises and protect your investment.

In this guide:

  1. Well systems and water testing

  2. Septic types, costs, and ROWP compliance

  3. Riparian areas, ditches, and creek setbacks

  4. Zoning, ALR rules, and permitted uses

  5. Rural access, utilities, and insurance factors


💧 1. Well Systems: Understanding Your Water Source

Most acreages in the Fraser Valley rely on private wells rather than city water. That means you’re responsible for both the quantity and quality of your home’s water supply.

What to check:

  • Well Type & Construction – Most modern acreages use drilled wells, while older ones may have dug wells. Understanding the depth, casing, and condition helps assess long-term reliability.

  • Capacity – A well’s flow rate (gallons per minute) determines whether it can meet household and irrigation needs — especially during dry Fraser Valley summers.

  • Water Quality – Fraser Health recommends bacteriological testing at least once a year, and chemical testing every few years or after major weather events.

  • Records & Registration – The provincial GWELLS database provides drilling logs, flow test results, and well IDs — always ask for these during due diligence.

  • Protection – Keep the wellhead sealed and clear of contaminants like fuel, livestock, or septic fields. Protecting your recharge area ensures safe, reliable water long-term.


🚽 2. Septic Systems: What Lies Beneath

Acreage properties usually rely on private septic systems instead of municipal sewer connections. Understanding your system’s type, condition, and maintenance history is crucial.

What to look for:

  • System Type – Common setups include:

    • Type 1: Tank and field

    • Type 2: Aerobic treatment

    • Type 3: Advanced treatment
      Each has unique costs, regulations, and maintenance needs.

  • Age & Condition – Tanks, pumps, and drain fields have limited lifespans based on care and soil type.

  • Regulation & Compliance – Must meet BC’s Sewerage System Regulation and be managed by a Registered Onsite Wastewater Practitioner (ROWP).

  • Maintenance Records – Pump-outs are typically required every 3–5 years. Always review service logs.

  • Setbacks & Future Plans – Septic fields must be a safe distance from wells, streams, and property lines, which may impact future additions or outbuildings.


🌊 3. Waterways & Classifications: More Than Meets the Eye

Creeks, ditches, and ponds can enhance a property’s appeal — but they also come with regulations and setbacks that can affect how you use your land.

Here’s what to keep in mind:

  • Riparian Protection – BC’s Riparian Areas Protection Regulation (RAPR) safeguards fish habitats and water quality. Setback zones (Streamside Protection & Enhancement Areas) must remain undisturbed.

  • Classifications – Waterways are labeled Class A, A(O), B, or C, each with its own rules for development and fencing.

  • Impact on Building – Even seasonal ditches can affect where you can build a shop, barn, or home. Some projects require an assessment from a Qualified Environmental Professional (QEP).

  • Property Value Consideration – Water features can boost aesthetics but also bring maintenance and compliance responsibilities.

  • Do Your Homework – Check municipal watercourse maps and zoning bylaws before planning changes.

    💡 Tip: Just because a creek looks dry in the summer doesn’t mean it’s not a regulated waterway.


📜 4. Zoning & Land Use: Know What’s Allowed

Not all acreages are created equal — zoning determines what you can (and can’t) do with your property.

Key points:

  • Zoning Basics – Each property falls under a bylaw (e.g. RU-1, RU-3 in Langley), which controls lot size, building setbacks, and permitted uses.

  • Agricultural Land Reserve (ALR) – Many Fraser Valley acreages are within the ALR, which regulates farming activities, secondary dwellings, and non-farm uses.

  • Shops & Secondary Homes – Zoning and ALR rules will determine what’s allowed — and how large you can build.

  • Title Restrictions – Covenants, easements, and building schemes may limit future development.

  • Municipal Variances & Permits – Some flexibility exists, but it typically requires approval from your municipality.


🚜 5. Access & Services: What to Expect in Rural Living

Acreage life often means more independence — but also more responsibility when it comes to services and infrastructure.

Consider the following:

  • Road Access – Many acreages use private lanes, gravel roads, or shared driveways. Check who’s responsible for upkeep and snow removal.

  • Easements & Rights-of-Way – Shared utilities or driveways can impact privacy and usage — always review your title.

  • Utilities – Hydro is common, but natural gas may not be available. Propane and satellite internet are common alternatives.

  • Waste & Snow Services – Garbage and recycling pickup may be limited; confirm with your local municipality.

  • Emergency Services – Distance from fire halls or hydrants can impact home insurance rates, so verify early in your buying process.


Acreage FAQ – Fraser Valley

Q: How do I test a well when buying an acreage?
A: Ask for recent flow and potability tests, confirm well depth/type, and review GWELLS records. If tests are old, request new bacteriological and chemical testing.

Q: How much does it cost to replace a septic system?
A: Costs vary by type and soil conditions, but replacements often range widely. Always confirm system type, age, and ROWP documentation during due diligence.

Q: Does a dry creek still affect what I can build?
A: Often yes. Seasonal waterways can still be regulated and require setbacks or environmental review.

Q: What is ALR and why does it matter on acreages?
A: The Agricultural Land Reserve restricts non-farm uses and can limit secondary homes, shops, or subdivision potential.

Q: Can I add a second home or large shop on an acreage?
A: Maybe — it depends on zoning, ALR rules, setbacks, and any covenants/easements on title.


🏠 Ready to Explore Acreage Life?

If you’re thinking about buying or selling an acreage in Langley, Abbotsford, Chilliwack, Mission, or anywhere in the Fraser Valley, we’ll walk you through wells, septic, zoning, and value factors before you commit.
Send us a quick message or call — we’re happy to review any property you’re considering and flag red-flags early.


As lifelong locals with both professional and personal experience in rural life — and with Ian’s background as a firefighter — we specialize in guiding clients through every detail with clarity and confidence.

📞 Reach out anytime — whether you’re just beginning your acreage journey or ready to make a move.
Let’s make sure your dream property truly fits your lifestyle.

Ask an Acreage Question

Tell us the area and budget you’re considering and we’ll flag any red-flags before you commit.

Browse Fraser Valley Listings

Tip: Use the Lot Size / Acres filter under ‘More’ to narrow to true acreage properties.

Read
Reciprocity Logo The data relating to real estate on this website comes in part from the MLS® Reciprocity program of either the Greater Vancouver REALTORS® (GVR), the Fraser Valley Real Estate Board (FVREB) or the Chilliwack and District Real Estate Board (CADREB). Real estate listings held by participating real estate firms are marked with the MLS® logo and detailed information about the listing includes the name of the listing agent. This representation is based in whole or part on data generated by either the GVR, the FVREB or the CADREB which assumes no responsibility for its accuracy. The materials contained on this page may not be reproduced without the express written consent of either the GVR, the FVREB or the CADREB.